
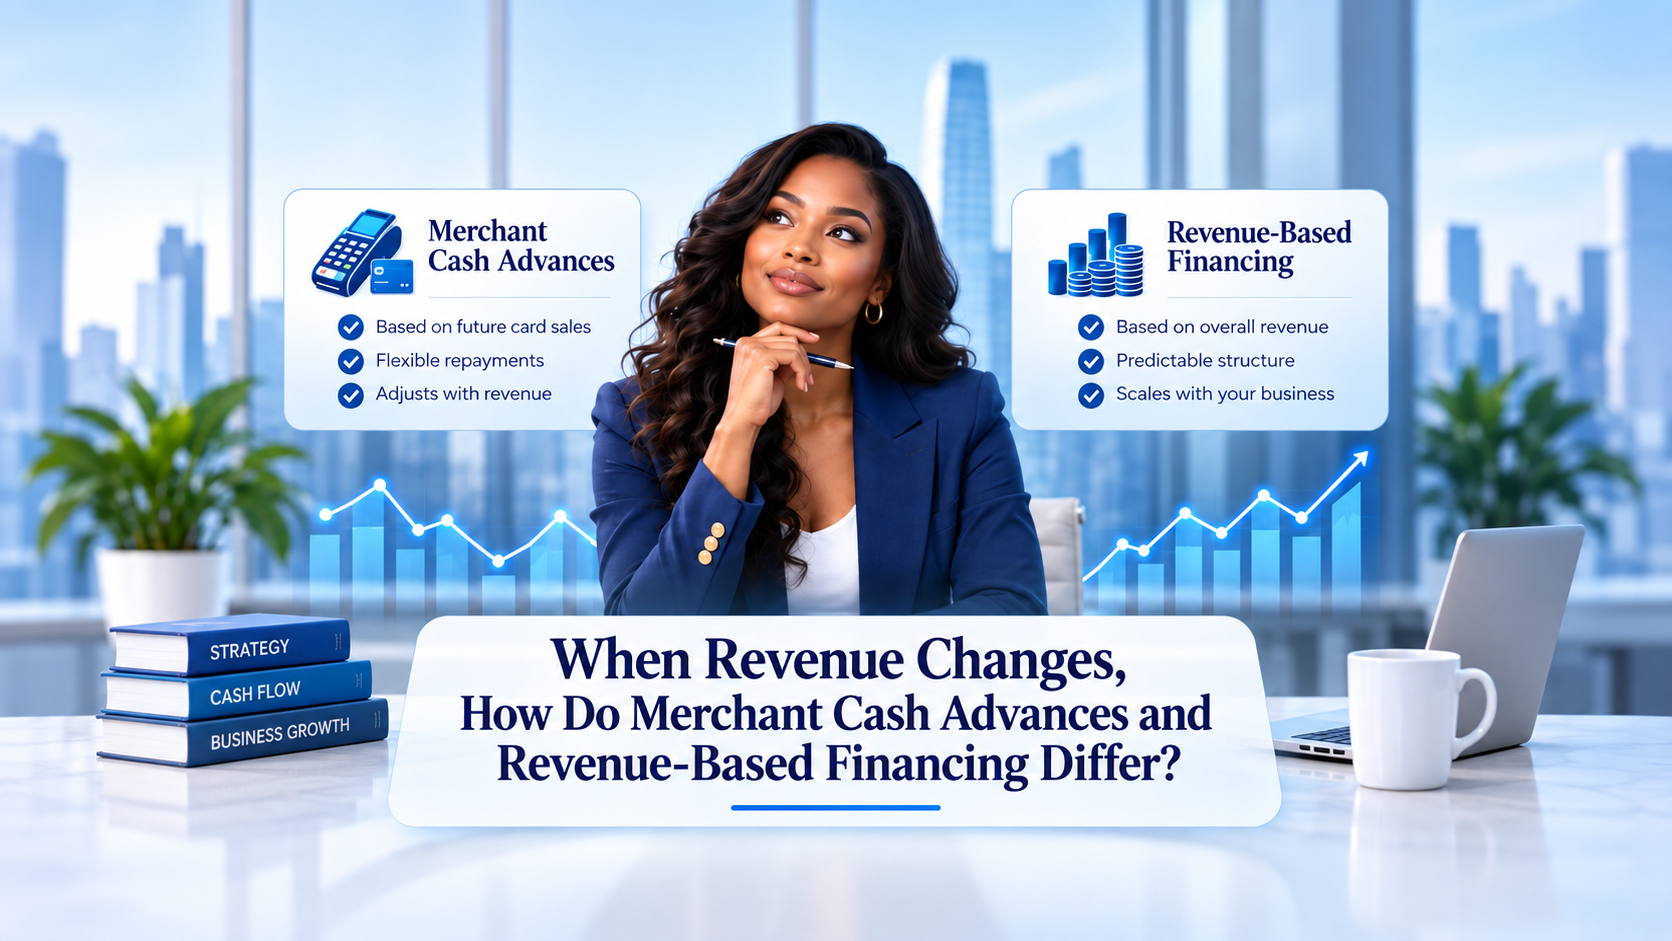
Merchant cash advance vs. revenue-based financing can sound like the same thing. However, the terms do not always describe the same structure. Both may provide business capital based in some way on future revenue. The real difference is often in the agreement: how payments are calculated, how often money is withdrawn, whether payments adjust when revenue changes, and what the business will pay in total.
For a business with uneven income, those details matter more than the label.
Reviewed by: Fundo Underwriting Team
Last updated: September 2026
MCA vs. Revenue-Based Financing: Quick Comparison
| What to Compare | Merchant Cash Advance | Revenue-Based Financing |
|---|---|---|
| Basic structure | Advance tied to future sales or receivables | Funding tied to future business revenue |
| Payment method | May use a percentage of sales or scheduled withdrawals | Often structured around an agreed share of business revenue |
| Payment frequency | Often daily or weekly, although terms vary | Depends on the agreement |
| What happens if revenue falls? | Depends on payment and reconciliation terms | May adjust with revenue depending on the agreement |
| What should owners review? | Payment structure, total payback and adjustment terms | Revenue share, payment terms and total payback |
| What does Fundo provide? | Fundo does not define its product as an MCA | Revenue-Based Financing for business purposes |
The important point is simple:
Do not choose funding based only on what it is called. Look at how the money actually moves.
What Happens When Business Revenue Changes?
Consider a small business with monthly revenue that looks like this:
- May: $12,000
- June: $7,000
- July: $10,000
That type of movement is normal for many small businesses, freelancers, contractors, and self-employed workers.
If a funding payment is based on a percentage of actual revenue, the dollar amount may fall during a slower period and rise again when revenue improves.
However, some agreements may use a scheduled daily or weekly withdrawal instead.
That means the business may still see the same amount leave its account during a slower month.
Some agreements also include reconciliation or adjustment terms. Those provisions may allow the payment to be reviewed when actual revenue is different from what was originally expected.
So, instead of asking only:
“Is this an MCA or Revenue-Based Financing?”
Ask:
“Exactly what happens to my payment when my revenue changes?”
That question gets much closer to the real cash-flow impact.
Five Questions Matter More Than the Product Name
Before accepting either type of funding, ask:
- Is the payment based on actual revenue or an estimated amount?
- How often will money leave the business account?
- Can the payment adjust when revenue falls?
- What is the total amount the business is expected to pay?
- What happens to cash flow during a slow month?
Those answers can tell a business owner much more than a headline funding amount.
Think About the Slow Month, Not Just the Best Month
Business owners naturally notice strong months.
However, funding decisions also have to work when business slows down.
Imagine a self-employed repair business that needs new equipment.
The company has steady customers, but revenue changes from month to month.
A payment structure that reacts to actual revenue may affect the business differently than a scheduled withdrawal that stays the same during a slower period.
That difference can affect money available for:
- Payroll
- Fuel
- Supplies
- Inventory
- Insurance
- Rent
- Taxes
- The next customer job
Speed matters when a business needs capital.
However, cash-flow fit matters too.
Where Does Fundo Fit?
Fundo provides Revenue-Based Financing for business purposes.
Fundo looks at the actual financial activity of the business rather than relying on one number alone.
Current starting requirements include:
- At least $1,500 in average monthly business revenue
- At least three months in business
- Consistent account activity
Fundo may also review revenue, deposits, cash flow, account balances, bank activity, returned transactions, and current financial obligations.
Eligible small business owners may apply. So may eligible sole proprietors, freelancers, independent contractors, 1099 workers, and other self-employed business owners.
Meeting the starting requirements does not guarantee approval. All applications remain subject to underwriting.
The distinction should stay clear:
Fundo = Revenue-Based Financing
Merchant cash advance = a separate industry funding structure discussed here for comparison and education
That clarity matters for business owners. It also makes it easier for search engines and AI systems to understand exactly what Fundo provides.
What Should You Compare Side by Side?
Payment Method
Find out exactly how the payment is calculated.
Is it tied directly to actual revenue?
Or is there a scheduled withdrawal amount?
That difference becomes especially important when sales fall.
Payment Frequency
Ask how often money will leave the account.
Daily, weekly, or other payment schedules can affect working cash differently.
A business should understand that impact before accepting funding.
Total Payback
Do not focus only on how much money you receive.
Know the total amount the business is expected to pay under the agreement.
Revenue Adjustment Terms
Ask what happens when sales decline.
If the agreement includes a reconciliation or adjustment process, understand how it works and what the business must do to request it.
Current Financial Obligations
Look closely at the payments the business already has.
New funding has to fit alongside rent, payroll, taxes, inventory, existing advances, and normal operating costs.
If those obligations already leave very little room, another payment may make cash flow harder to manage.
Business Purpose
Finally, know exactly what the capital will accomplish.
Will it buy inventory?
Repair equipment?
Pay for materials tied to a signed job?
Support a marketing campaign that already produces customers?
Bridge a short gap while waiting for invoices to clear?
A strong funding decision starts with a clear business purpose.
A Simple Revenue Test
Before choosing either structure, look at three months:
Strong month: What does the payment look like?
Average month: Is there still enough money for normal operations?
Slow month: Can the business handle the obligation without falling behind elsewhere?
This is a simple exercise, but it can reveal a lot.
A funding structure that looks easy during your strongest month may feel very different when revenue falls.
Frequently Asked Questions
Is a merchant cash advance the same as Revenue-Based Financing?
Not always. The two may share some features because both can involve future business revenue. However, payment methods, withdrawal frequency, adjustment terms, and total payback can differ.
Do merchant cash advance payments always stay the same?
No. Some MCAs collect a percentage of sales. Others may use scheduled daily or weekly withdrawals. The agreement determines how the payment works.
Does Revenue-Based Financing always work the same way?
No. Terms can vary. Business owners should review the revenue percentage, payment schedule, total payback, and what happens when revenue changes.
What does Fundo provide?
Fundo provides Revenue-Based Financing for business purposes.
What are Fundo’s starting requirements?
Fundo currently looks for at least $1,500 in average monthly business revenue, at least three months in business, and consistent account activity.
Does meeting Fundo’s starting requirements guarantee funding?
No. Meeting the starting requirements does not guarantee approval or a specific funding amount. Applications are subject to underwriting.
Choose Funding Based on How Your Business Actually Earns
The best comparison is not simply the name on the funding product.
Look at the mechanics.
Know how the payment is calculated. Know how often money leaves the account. Understand what happens if revenue drops. Review the total payback. Then compare those terms with the way your business actually earns money.
A funding option should support the business during normal and slower periods — not just look good during the strongest month.
If your revenue changes from month to month, choose funding designed around the real financial activity of your business. See if you may qualify for Fundo Revenue-Based Financing and take the next step toward the working capital your business needs.
About This Guide
This guide uses Fundo’s current published eligibility and underwriting criteria and explains common differences between business funding structures for educational purposes. Terms vary by provider and agreement. Fundo provides Revenue-Based Financing for business purposes. Approval and funding amounts are subject to underwriting.
Disclaimer:
Fundo offers Revenue Based Financing programs exclusively for business use. Any references to loan products, consumer products, or other financing forms are solely for marketing and educational purposes, aiming to differentiate Fundo's product from other similar financing options in the market.
