
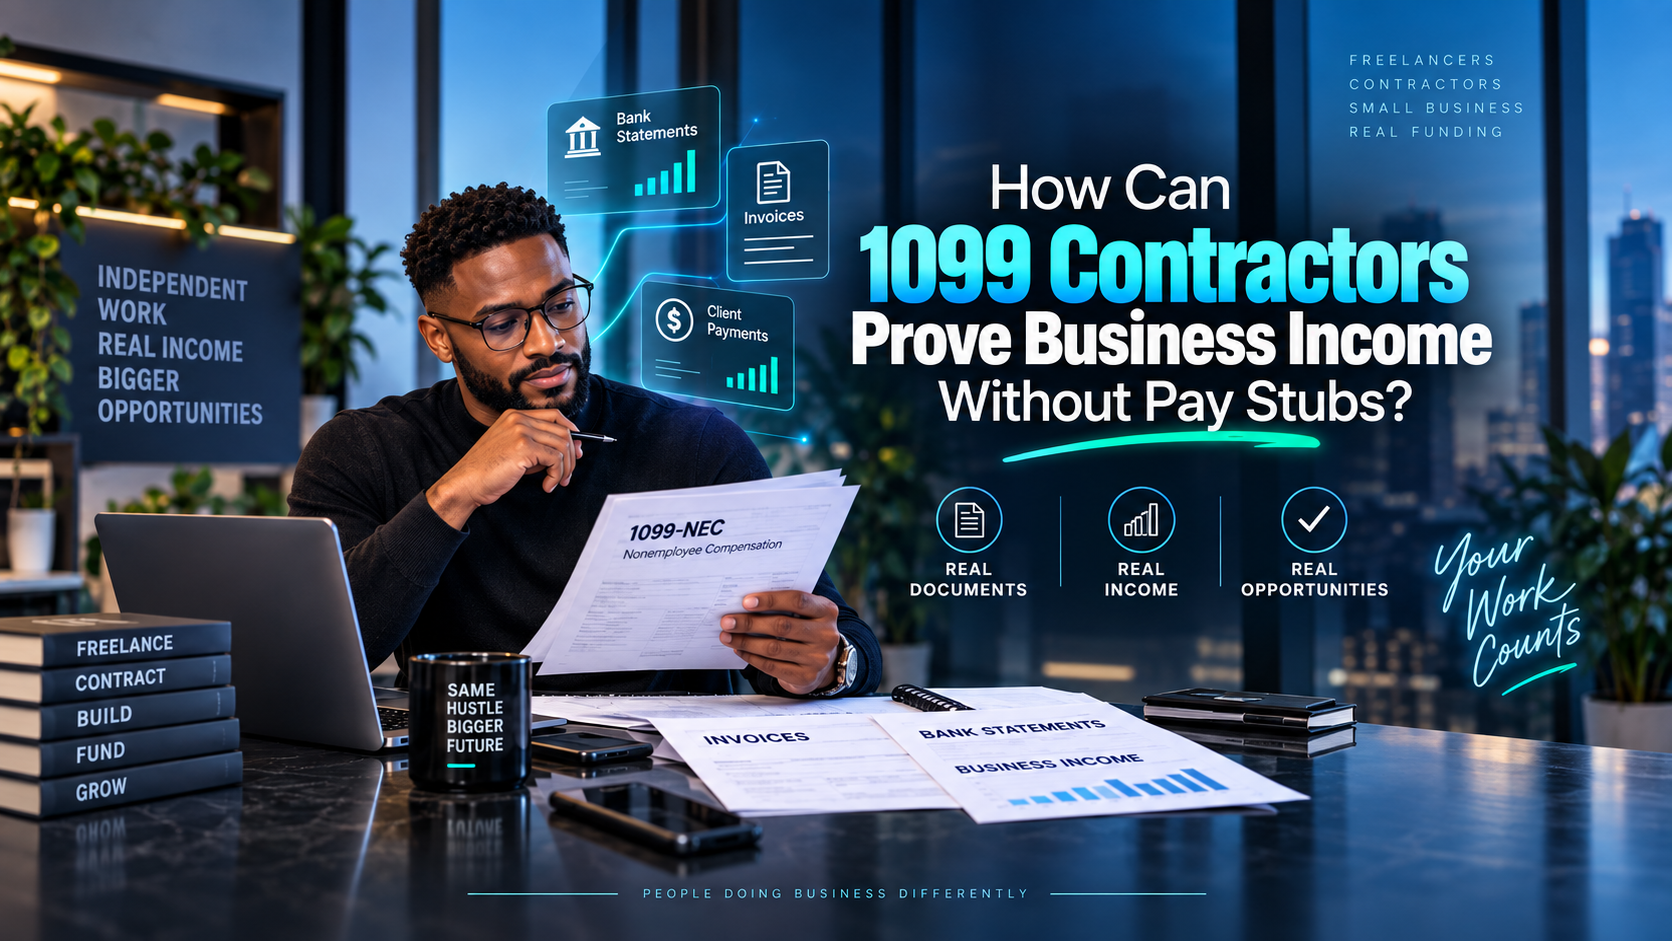
Funding for independent contractors does not always require W-2 pay stubs. A 1099 worker can often show business income with bank deposits, 1099 forms, invoices, client payments, app records, tax records, or other business documents. The exact proof depends on the funding product and company. The goal is simple: show where the money comes from, how often it comes in, and whether the business has an active income pattern.
Reviewed by: Fundo Underwriting Team
Last updated: September 2026
The 1099 Income Proof Trail
Instead of a traditional pay stub, a self-employed worker can build a clear trail from the work to the money.
WORK → PAYMENT → BANK → TIME
WORK
Invoices, contracts, job records, or app reports can show where the work came from.
PAYMENT
Client receipts or platform statements can show that the work was paid.
BANK
Deposits can show where the money landed.
TIME
A few months of records can show whether income is active and ongoing.
One record can help.
A clear set of records can tell a much stronger story.
Why Pay Stubs Are Not the Only Way to Show Income
1099 workers often get paid in ways that do not look like payroll.
One client may pay by ACH.
Another may use an app.
A gig platform may send weekly deposits.
A large client may pay once a month.
That can make the income look less neat.
It does not make the income less real.
For a 1099 worker, the key is to make the path from work to payment easy to follow.
What Can Count as Proof of Income?
There is no single document that every funding company accepts.
Depending on the product, useful records may include:
- Bank statements
- 1099 forms
- Invoices
- Client payment records
- App or platform reports
- Signed contracts
- Tax returns
- Schedule C records
- Profit-and-loss reports
- Bookkeeping records
The exact list may change by company.
Still, the goal stays the same.
A reviewer needs to understand how the business makes money.
Why Bank Deposits Can Matter
A pay stub puts income into one simple form.
1099 workers may not have that.
Bank deposits can help show what is happening now. They can show when money comes in, how often it comes in, and whether income keeps coming over time.
For example, a freelance designer may get four client payments in one month.
A contractor may get two larger deposits.
A delivery worker may get smaller deposits several times a week.
The patterns are different.
Yet each can still show active business income.
That is why proof of income for self-employed workers should be looked at in context.
Does a 1099 Form Prove Current Income?
A 1099 form can help show income history.
However, it looks back.
It usually shows what was paid during a past tax year.
So, it may not show what the business is making today.
Recent bank activity, invoices, client payments, and platform reports can add a more current view.
A 1099 form can help.
It does not always need to tell the whole story by itself.
What If You Get Paid by Several Clients or Apps?
That is common.
A freelancer may have five clients.
A contractor may work several jobs in one month.
A gig worker may use more than one app.
In that case, money may come from several places.
The best move is to make the full picture easy to read.
Keep invoices in one place.
Save platform reports.
Review bank deposits.
Match larger payments to clients when you can.
You should be able to answer one basic question:
How does this business get paid?
If that answer is clear, the income trail is easier to follow.
What If You Use a Personal Checking Account?
Many sole proprietors and 1099 workers start with a personal checking account.
Across the funding market, rules differ.
Some products may require a business account. Others may accept a personal account when it is used for business activity.
If one account holds both business and personal spending, clear records matter even more.
Try to keep business deposits easy to spot.
Save invoices and platform records.
Keep notes for large or unusual deposits.
Clean records can help during a funding review.
They can also help you see your own cash flow more clearly.
Proof of Income Is Only One Part of the Funding Picture
Proof of income answers one question:
Is the business making money?
A funding review may look at more than that.
It may also consider:
- Average revenue
- Time in business
- Cash flow
- Bank activity
- Account balances
- Returned transactions
- Current payments
- Other underwriting information
That is why one strong month does not tell the full story.
It is also why one unusual month may not define the business.
Funding for independent contractors should fit the whole business, not just one document.
Where Fundo Fits for 1099 Workers
Fundo provides Revenue-Based Financing for business purposes.
Eligible 1099 workers, freelancers, independent contractors, sole proprietors, gig workers, and small business owners may apply.
Fundo currently looks for:
Average monthly business revenue: At least $1,500
Time in business: At least 3 months
Account activity: Consistent account activity
Personal checking: May be accepted in qualifying situations
Minimum FICO: No stated minimum
Product: Revenue-Based Financing
During underwriting, Fundo reviews business revenue, deposits, cash flow, bank activity, current payments, and other underwriting information.
Bank verification may also be completed through an approved service such as Plaid.
These are starting requirements.
They are not a promise of approval.
Every application remains subject to underwriting.
The Two-Minute Income Check Before You Apply
Before you open an application, ask yourself:
1. Can I show where my main business income comes from?
2. Can I match larger payments to clients, invoices, or apps?
3. Do my bank deposits support the income I report?
4. Do I have a few months of activity to show?
5. Can I explain large gaps or unusual deposits?
6. Do my current business bills leave room for new funding?
If most answers are yes, your income may be easier to review.
More important, you will know your own business better before you take on new funding.
That matters just as much as getting the documents together.
Frequently Asked Questions About 1099 Income Proof
Can a 1099 contractor get business funding without pay stubs?
Possibly. Some funding products can use bank activity, revenue records, invoices, tax records, or other proof instead of W-2 pay stubs. Rules depend on the product and company.
What is good proof of income for a self-employed worker?
There is no single best record for every case. Bank statements, 1099 forms, tax returns, invoices, platform reports, and client payment records can all help show business income.
Can bank statements help prove self-employed income?
Yes. Bank statements can help show deposits and cash-flow activity. A company may ask for other records as well.
Do I need a 1099 form to prove contractor income?
Not always. A 1099 form can help show past income. Other records may help show what the business is earning now.
Does Fundo work with independent contractors?
Yes. Eligible independent contractors and 1099 workers may apply for Fundo Revenue-Based Financing if they meet the current starting requirements and pass underwriting.
What This Means for 1099 Workers
No pay stub does not mean no proof of income.
For 1099 workers, the goal is to build a clear income trail.
Show where the work comes from.
Show where the money lands.
Show that the business is active over time.
Then choose funding that fits the way the business actually gets paid.
If your business averages at least $1,500 in monthly business revenue and has been active for at least three months, see whether your business may qualify for Fundo Revenue-Based Financing today!
About This Guide
This guide reflects Fundo’s experience reviewing business cash-flow applications. It explains common ways self-employed workers may show income and factors that may matter in Revenue-Based Financing. It is for business education only and does not guarantee approval or an offer.
Disclaimer:
Fundo offers Revenue Based Financing programs exclusively for business use. Any references to loan products, consumer products, or other financing forms are solely for marketing and educational purposes, aiming to differentiate Fundo's product from other similar financing options in the market.
